While the world of higher education (and sponsored research in particular) is often filled with lots of acronyms, one very prevalent acronym is MTDC. MTDC, which stands for Modified Total Direct Costs, functions in two primary ways:
- It represents the most common denominator of an institution’s negotiated Facilities and Administrative (F&A) rates - which are calculated as a fraction and expressed as a percentage, and
- It is the portion of an individual sponsored award’s direct costs to which the institution’s applicable F&A rate for that award is applied.
A screen shot of Georgia Tech’s current F&A Rate Agreement is shown below, with our definition of MTDC described under the Distribution Bases section.
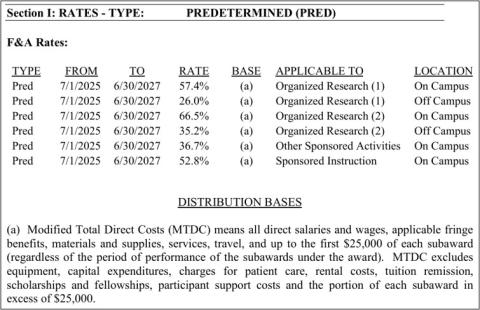
The “exclusions” section of the definition is particularly relevant, because any cost directly charged to a sponsored award in one of these categories is not only excluded from the denominator of our calculations for our proposed and negotiated rates, but it will also NOT be assessed the F&A rate when subsequently charged to a sponsored award. The underlying rationale is that excluded costs generally do not generate institutional administrative or facilities burden in the same proportion as salaries, supplies, and routine sponsored activity.
As a result of MTDC:
- The direct costs on an award will often be a mix of costs that bear F&A and costs that do not.
- Two awards with the same total direct costs can produce different F&A recovery amounts because one award may have a different ratio of MTDC to non-MTDC than the other award.
- An award containing substantial equipment, tuition, participant support, or large subawards will have a lower effective F&A percentage than an award without these costs.
If you have any questions on the contents of this article, please contact Josh Rosenberg at josh.rosenberg@business.gatech.edu.